The global deal market entered 2026 with extraordinary momentum.
Mega-deals returned.
Artificial intelligence triggered enormous strategic investment.
Private equity firms regained confidence.
Companies began pursuing acquisitions to gain technology, scale and market share.
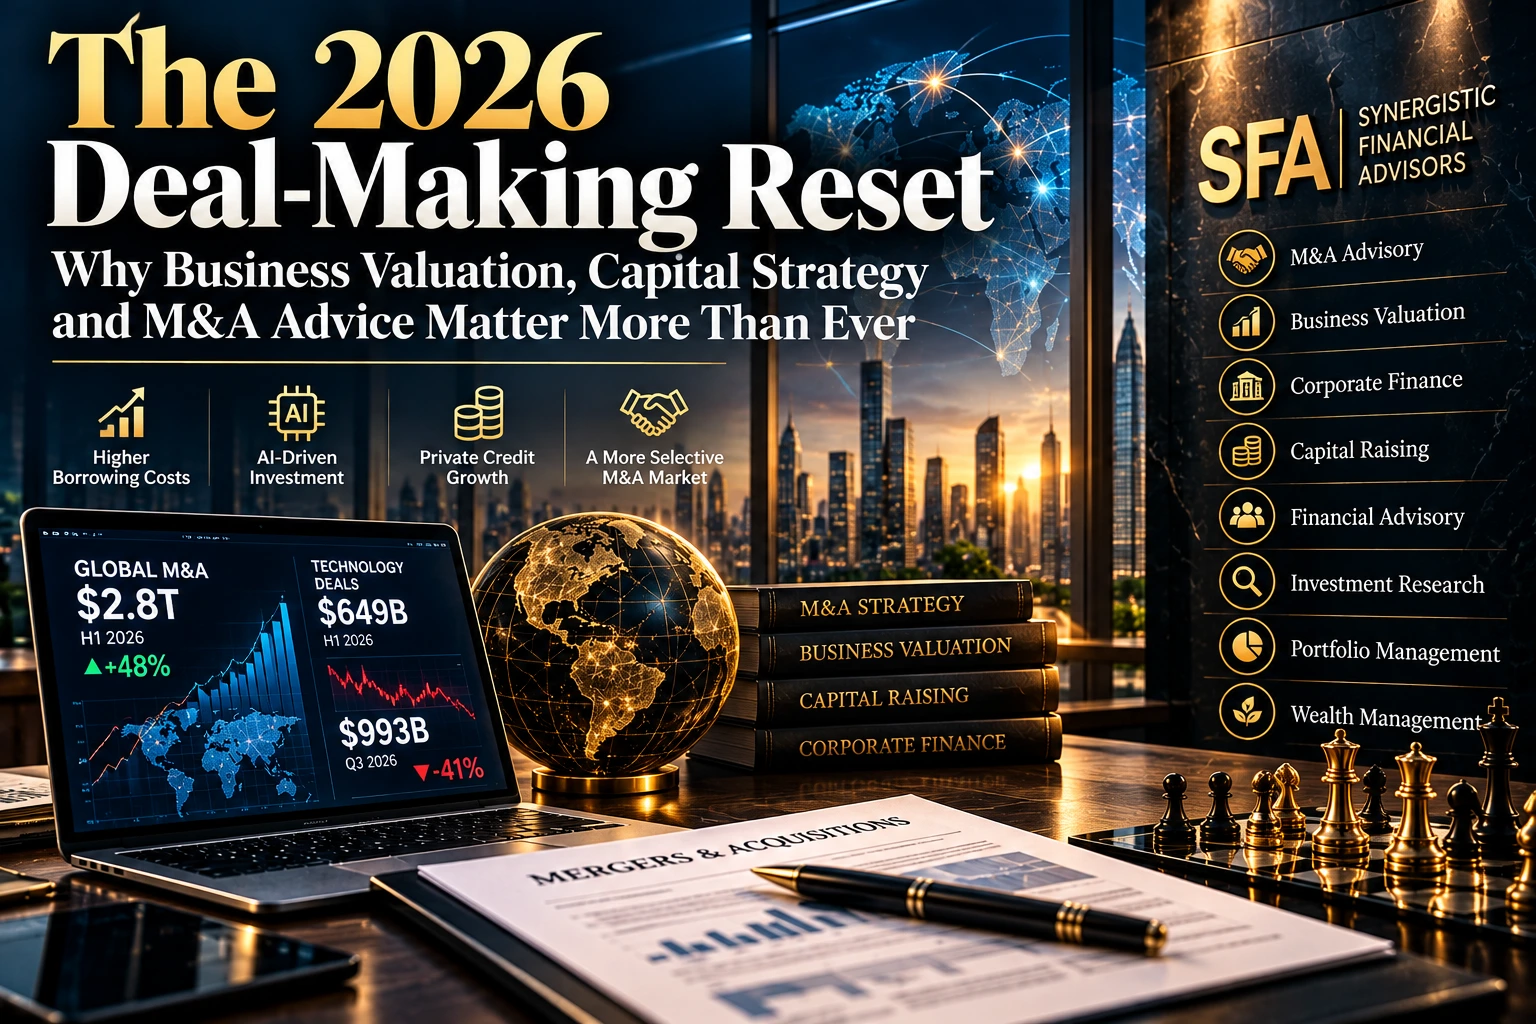
During the first half of 2026, global announced mergers and acquisitions reached approximately $2.8 trillion, up 48% from the same period a year earlier. Technology led all sectors with roughly $649 billion of announced deals.
Then the environment changed.
Global M&A volume fell to approximately $993 billion in the third quarter, down 41% from Q2 and marking the first quarter below $1 trillion since the second quarter of 2025. Rising borrowing costs, changing valuations and financial-market uncertainty began making buyers more selective.
At the same time, companies building the infrastructure behind the AI boom are facing a new reality: capital is becoming more expensive, and investors increasingly want evidence that enormous technology investments can generate adequate returns.
For business owners, boards and investors, this creates an important shift.
The central question is no longer simply:
“Can we raise capital or complete a transaction?”
It is:
“Can we complete the right transaction, at the right valuation, with a capital structure that still makes financial sense?”
That is why corporate finance advisory, business valuation, M&A strategy and capital planning may become even more important in late 2026 and 2027.
From M&A Boom to M&A Discipline
The first half of 2026 demonstrated that companies remain willing to pursue large strategic transactions.
According to LSEG data reported by Reuters, 47 transactions worth more than $10 billion were announced during the first half of the year, totaling roughly $1.3 trillion.
Companies were pursuing scale.
Technology firms were buying capabilities.
Private-equity sponsors were looking for large opportunities.
Boards were again willing to consider transformative deals.
But Q3 showed something equally important:
Capital markets can change faster than corporate strategy.
Higher interest rates increase acquisition financing costs.
Volatile markets make valuations harder to agree on.
Uncertain economic conditions can make buyers more cautious.
And when the cost of capital rises, a transaction that looked attractive six months ago may no longer produce the same expected return.
This is why disciplined M&A advisory services go beyond finding a buyer or acquisition target.
The financial case for a transaction needs to be tested under realistic assumptions.
Business Valuation Matters More When Markets Become Uncertain
In strong markets, sellers often become anchored to high valuations.
Buyers may also be more willing to pay aggressive multiples because financing is easier and future growth appears more certain.
A tougher market exposes the difference between:
the price an owner wants
and
the value a buyer can financially justify.
Professional business valuation services can help companies evaluate value using factors such as:
- Revenue
- EBITDA and profitability
- Cash generation
- Growth expectations
- Debt
- Customer concentration
- Competitive position
- Industry outlook
- Comparable transactions
- Comparable public companies
- Future cash flows
- Cost of capital
Valuation should also examine risks that headline financial statements may not fully reveal.
A company may be profitable but heavily dependent on one customer.
Another may have rapid revenue growth but weak cash conversion.
A technology company may have an attractive product but require substantial future capital.
Two businesses with similar revenues can therefore have dramatically different values.
AI Is Creating a New Valuation Challenge
Artificial intelligence is one of the strongest forces shaping corporate investment in 2026.
But AI is also making valuation more complicated.
Companies are spending enormous amounts on:
- Data centers
- GPUs and semiconductors
- Energy infrastructure
- Cloud capacity
- Software
- AI talent
- Enterprise automation
The question investors are increasingly asking is:
What return will all this spending produce?
Reuters reported on October 15 that the market selloff and higher interest rates are already challenging some companies involved in AI infrastructure financing. Investors are demanding stronger evidence that businesses can absorb higher financing and computing costs while still generating acceptable returns.
This has major implications for valuation.
A company should not automatically receive a premium simply because it is associated with AI.
Instead, investors may increasingly examine:
AI investment → revenue growth → margins → free cash flow → return on invested capital
That is fundamentally a corporate-finance problem.
The Cost of Capital Can Change an Acquisition Completely
Imagine a company considering a $100 million acquisition.
Management believes the target can generate attractive growth and cost synergies.
But part of the purchase will be financed through debt.
If borrowing costs rise materially, the expected return on the deal can fall.
Management must then reconsider:
- Purchase price
- Debt structure
- Equity contribution
- Expected synergies
- Integration costs
- Cash-flow coverage
- Exit assumptions
A good acquisition is not simply a good company.
It also needs to be acquired at a price and financing structure that make financial sense.
That is where financial analysis and corporate finance advisory become critical.
Private Credit Has Plenty of Money—but Deal Quality Still Matters
Another important 2026 development is the enormous amount of capital flowing into private credit.
Direct-lending funds raised roughly $129 billion during the first nine months of 2026, up 35% from the previous year and the highest nine-month fundraising total in at least a decade.
At the same time, direct-lending volume declined 28% year over year in Q3 to about $49.8 billion.
This creates an interesting situation:
Lenders have more capital—but fewer attractive transactions in which to deploy it.
Competition between lenders may create better financing options for some borrowers.
But companies should not assume that readily available debt automatically means they should borrow more.
Management still needs to ask:
- What is the true cost of financing?
- Is the debt fixed or floating?
- What covenants apply?
- How much cash flow supports the debt?
- What happens if revenue falls?
- Can the company refinance later?
- Is debt preferable to raising equity?
That is capital structure strategy, not simply fundraising.
Capital Raising Should Start With the Purpose of Capital
Companies frequently begin financing discussions with:
“How much money can we raise?”
A stronger question is:
“What return can we generate on the money we raise?”
Capital may be used for:
- Expansion
- Acquisition
- Working capital
- Technology
- New markets
- Debt refinancing
- Product development
- Ownership restructuring
Each use has a different risk and expected return.
Effective capital raising advisory should therefore begin with the investment case.
For example:
If a business raises $20 million at a high cost of capital and deploys it into projects generating weak returns, the financing may reduce shareholder value.
Raising capital is not itself success.
Creating value with the capital is.
Should Businesses Use Debt or Equity?
There is no universal answer.
Debt
Advantages can include:
- Existing shareholders maintain ownership
- Interest may be cheaper than equity capital
- Predictable financing structure
But risks include:
- Mandatory payments
- Refinancing exposure
- Financial covenants
- Greater vulnerability during downturns
Equity
Equity does not usually require scheduled repayment.
But it can dilute existing shareholders.
New investors may also require:
- Board participation
- Governance rights
- Return targets
- Exit rights
The right structure depends on profitability, cash flow, growth, risk, valuation and strategic objectives.
That is why financing decisions belong within broader financial management.
Business Owners Should Know Their Value Before They Need a Transaction
Many entrepreneurs wait until they receive an acquisition offer before thinking seriously about valuation.
That is often too late.
Understanding business value years before an exit can help owners identify what is preventing the company from receiving a stronger valuation.
Potential value drivers include:
Recurring Revenue
Predictable revenue can be attractive to buyers.
Customer Diversification
Heavy reliance on one or two customers can reduce value.
Management Depth
A company dependent entirely on its founder may be harder to transfer.
Profitability
Buyers generally care about sustainable cash generation, not simply revenue growth.
Financial Reporting
Reliable financial information reduces uncertainty.
Competitive Advantages
Technology, brands, intellectual property, customer relationships and distribution networks can increase strategic value.
Growth Opportunities
Buyers frequently pay for future opportunity—but only when the opportunity is credible.
This makes business valuation not only a transaction exercise but also a strategic management tool.
M&A Is Also an Exit-Planning Decision
For founders, selling a company is rarely purely corporate.
It can completely change the owner’s personal financial position.
Before a transaction, most personal wealth may be concentrated in one private business.
After the transaction, the owner may suddenly hold:
- Cash
- Public securities
- Earn-outs
- Seller financing
- Rollover equity
- Other financial assets
The financial problem changes from:
“How do I increase the value of my company?”
to:
“How do I manage the wealth created by selling it?”
This is where corporate finance can connect naturally with wealth management, portfolio management, investment management and long-term financial planning.
Buyers Also Need Better Due Diligence
The current market is not only challenging sellers.
Buyers face risks too.
Before completing an acquisition, companies should test:
- Quality of earnings
- Cash flow
- Working capital
- Debt
- Customer concentration
- Supplier dependency
- Technology risks
- Integration requirements
- Synergies
- Valuation
- Financing
- Downside scenarios
A target may appear attractive during initial discussions.
Financial due diligence may reveal a different picture.
This is why disciplined buyers should be willing to walk away when the numbers do not support the strategy.
Completing fewer good transactions is usually better than completing more bad ones.
Cross-Border M&A Continues to Create Opportunities
Despite the Q3 slowdown, global dealmaking remains substantial.
Fintech provides one example.
KPMG reported global fintech investment of approximately $103.1 billion in the first half of 2026, with M&A accounting for roughly $67.9 billion. Cross-border M&A represented around $20.2 billion as companies sought scale and new capabilities internationally.
Cross-border acquisitions can provide:
- New markets
- Technology
- Distribution
- Customers
- Talent
- Geographic diversification
But they also introduce:
- Currency risk
- Regulatory complexity
- Different tax systems
- Political risk
- Integration challenges
This makes professional transaction analysis particularly important.
Seven Questions Every Business Owner Should Ask in Late 2026
Before raising capital, buying a company, selling a business or restructuring ownership, ask:
1. What is the company realistically worth today?
Not what you hope it is worth.
What can financial analysis support?
2. What factors could increase the valuation?
Margins? Revenue quality? Management? Customer diversification?
3. What is the company’s true cost of capital?
Debt and equity both have costs.
4. How much leverage can cash flow safely support?
Do not evaluate debt only under optimistic assumptions.
5. Would an acquisition create more value than organic growth?
Sometimes buying growth makes sense.
Sometimes building internally is cheaper.
6. Is now the right time to sell?
Consider both market conditions and company-specific readiness.
7. What happens to the owner’s wealth after a transaction?
Exit planning should include personal financial strategy.
2026 Corporate Finance Checklist
| Decision | Key Question |
|---|---|
| Business Valuation | What is the company realistically worth? |
| M&A | Does the transaction create shareholder value? |
| Capital Raising | What will the capital actually fund? |
| Debt | Can cash flow comfortably support repayment? |
| Equity | Is dilution justified by future growth? |
| Acquisition | Are expected synergies realistic? |
| Sale | Is the company prepared for buyer due diligence? |
| Restructuring | Can capital or operations be improved? |
| AI Investment | What financial return should technology spending produce? |
| Exit Planning | What happens to the owner’s wealth afterward? |
How SFA Can Help Businesses Navigate the 2026 Deal Market
The current market environment directly connects with the core capabilities of Synergistic Financial Advisors (SFA).
Businesses considering growth, financing, restructuring or transactions may require more than one isolated service.
SFA’s capabilities include areas such as:
Corporate Finance
Helping businesses evaluate financing, transactions and strategic capital decisions.
Business Valuation
Assessing business value through financial analysis, market evidence and future cash-flow expectations.
M&A Advisory
Supporting buyers and sellers through transaction analysis, valuation, negotiation and strategic decision-making.
Capital Sourcing
Helping businesses evaluate funding alternatives and appropriate capital structures.
Financial Analysis and Research
Providing the information required for better investment and strategic decisions.
Strategic and Exit Planning
Helping business owners prepare companies for long-term growth, succession or a future transaction.
For business owners, SFA can also help connect corporate decisions with broader financial objectives.
Business Value → Transaction Strategy → Liquidity → Portfolio Management → Long-Term Wealth
That wider perspective becomes particularly useful when a company represents a large portion of the owner’s personal net worth.
Final Thoughts
The second half of 2026 is showing businesses an important lesson.
Strong deal markets do not eliminate the need for financial discipline.
Global M&A surged during the first half of the year, but Q3 activity dropped sharply as borrowing costs and market uncertainty increased.
AI investment continues to create enormous opportunities, but investors are increasingly demanding evidence that capital spending will generate sustainable returns.
Private credit funds have unprecedented amounts of capital, yet lenders themselves are competing to find attractive places to deploy it.
Together, these developments create a more selective financial environment.
Companies can still grow.
Capital remains available.
Transactions are still happening.
But the market is increasingly rewarding one thing:
Financial discipline.
Know what your business is worth.
Understand your cost of capital.
Raise money for a clear purpose.
Do not overpay for acquisitions.
Prepare properly before selling.
And evaluate every major transaction according to whether it creates long-term value.
That is the difference between simply completing a deal and completing a good deal.