Choosing professional financial help can be surprisingly confusing.
You search for a financial advisor and find investment firms. You search for an investment advisor and discover professionals offering retirement planning. Then you search for a financial planner and find someone who also manages investment portfolios.
So what is the actual difference?
The short answer is:
The titles can overlap. The services, credentials, regulatory status, compensation structure and legal obligations are what you need to investigate.
The U.S. Securities and Exchange Commission explains that financial professionals may use a variety of titles, while federal securities laws distinguish between legal entities such as investment advisers and broker-dealers. The SEC also notes that some financial planners and investment advisers provide comprehensive financial plans, while others focus more narrowly on investments.
That distinction matters because the person you hire could be helping you with one specific investment decision — or helping coordinate your entire financial life.
This guide breaks down the three terms and explains what to look for before choosing professional financial guidance.
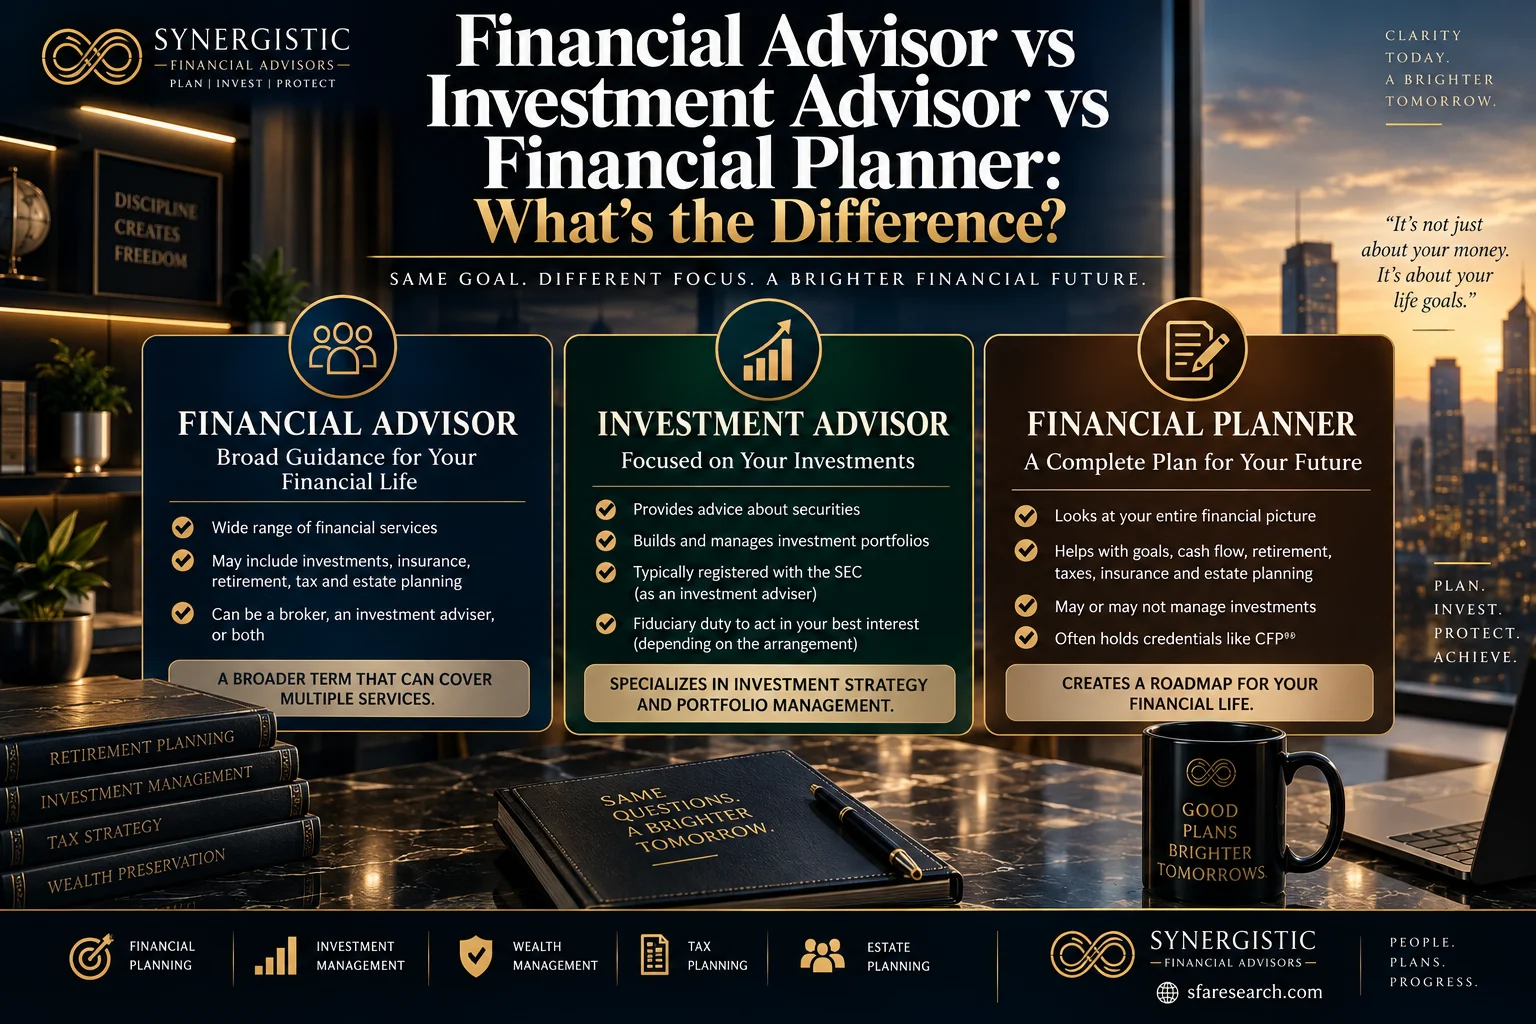
Financial Advisor: The Broadest Term
“Financial advisor” is generally a broad industry term rather than one single professional designation.
A financial advisor may help clients with:
- Investments
- Retirement
- Insurance
- Cash-flow planning
- Estate considerations
- Tax strategy
- Wealth management
- Business finances
But the exact services depend on the individual or firm.
That is why simply searching for the best financial advisors is not enough.
You need to determine what a particular advisor actually does.
The SEC has specifically warned that financial professionals may use many different titles, including “financial advisor,” “financial consultant,” and “wealth manager.” The title itself does not tell you everything about the regulatory relationship.
A financial consultant may therefore provide services that overlap significantly with those offered by a financial advisor.
The important question is:
What exactly are you paying this professional to do?
Investment Advisor: A More Specific Regulatory Meaning
“Investment advisor” can have a specific legal meaning under U.S. securities law.
The SEC generally describes an investment adviser as a person or firm that, for compensation, is in the business of providing advice about securities or issuing analyses concerning securities.
This is different from simply calling yourself an investment professional.
An investment adviser may provide advice about:
- Stocks
- Bonds
- Mutual funds
- ETFs
- Investment portfolios
- Asset allocation
- Securities selection
Investment advisers can operate under different structures, including registered investment advisers and other regulated arrangements.
This is why someone looking for an investment advisor should investigate the actual firm and professional relationship rather than relying on the title alone.
Financial Planner: Focused on the Bigger Financial Picture
A financial planner generally focuses on connecting different areas of a person’s financial life.
That can include:
- Income
- Spending
- Saving
- Investments
- Insurance
- Retirement
- Taxes
- Estate considerations
- Major financial goals
The SEC notes that some financial planners provide comprehensive financial plans that assess different aspects of a person’s financial life and develop strategies around their goals.
However, the term “financial planner” itself does not automatically mean the professional holds a particular certification.
CFP Board states that virtually anyone can use the title “financial planner,” while CFP® professionals must meet its education, examination, experience and ethics requirements.
That makes credentials important.
What Is a Certified Financial Planner?
A certified financial planner — more precisely, a CFP® professional — has completed requirements established by CFP Board.
According to CFP Board, CFP® certification involves rigorous requirements including education, examination, experience and ethical standards. CFP® professionals also commit to acting as fiduciaries when providing financial advice to clients.
That does not mean every person without the CFP® designation provides poor advice.
It means the designation represents a specific certification framework that consumers can investigate.
When comparing professionals, ask:
- What credentials do you hold?
- Who issued them?
- What requirements were involved?
- What services do they cover?
- What standard of conduct applies to your relationship?
Financial Advisor vs Investment Advisor vs Financial Planner
Here is the simplest way to think about the three terms:
| Professional Term | Typical Focus | What to Investigate |
|---|---|---|
| Financial Advisor | Broad financial guidance | Services, licensing, compensation and legal relationship |
| Investment Advisor | Investment and securities advice | Registration, services, fees and conflicts |
| Financial Planner | Broader financial strategy | Planning process, credentials and scope |
| CFP® Professional | Comprehensive financial planning credential | CFP Board certification and fiduciary commitment |
The boundaries can overlap.
A single professional could potentially provide financial planning, investment advice and broader advisory services.
That is why the question should not simply be:
“Which title is better?”
Instead ask:
“Which services do I need, and which professional is qualified and structured to provide them?”
The Difference Between Financial Planning and Investment Management
This is one of the most important distinctions for consumers.
Imagine you have $500,000 invested.
An investment-focused professional may concentrate on:
- Asset allocation
- Security selection
- Portfolio construction
- Risk
- Investment performance
A comprehensive financial planner may additionally examine:
- Retirement income
- Taxes
- Insurance
- Cash flow
- Estate considerations
- Education funding
- Major purchases
Neither approach is automatically appropriate for every person.
Your needs determine the scope of service.
Someone who only wants help constructing an investment portfolio may need something different from a family trying to coordinate retirement, taxes, estate planning and long-term wealth.
Where Wealth Management Fits In
Wealth management often brings multiple financial services together.
Depending on the firm, wealth management can include:
- Financial planning
- Investment management
- Portfolio management
- Retirement planning
- Tax planning
- Estate considerations
- Risk management
The term itself does not guarantee a particular service model.
Always ask what is included.
For a high-net-worth family, for example, the relationship may involve much more than investment selection.
The family may need coordination between investments, tax strategy, business interests, estate planning and long-term wealth transfer.
What Does Portfolio Management Mean?
Portfolio management focuses on managing a collection of investments according to a client’s objectives and constraints.
That can involve decisions about:
- Asset allocation
- Diversification
- Risk exposure
- Rebalancing
- Investment selection
- Liquidity
A portfolio manager may therefore work primarily with investments rather than every aspect of a client’s financial life.
This distinction matters when evaluating an investment management relationship.
Ask whether the professional is:
Managing investments only — or integrating those investments into a broader financial plan?
How Fees Can Differ
Another major difference is compensation.
Financial professionals may be compensated through different structures, including:
- Asset-based advisory fees
- Hourly or project fees
- Flat planning fees
- Commissions
- A combination of compensation methods
The SEC advises consumers to ask how much their professional is paid and understand what fees mean in actual dollar terms.
FINRA also notes that brokerage and advisory relationships can involve different fee structures and that consumers should understand the services and costs associated with the relationship they choose.
A fee that appears small as a percentage can still represent a significant dollar amount as your assets grow.
For example, a 1% annual fee on $500,000 is $5,000 per year before considering compounding effects.
So always ask:
“How much will I actually pay?”
What Does Fiduciary Mean?
“Fiduciary” is another term that deserves attention.
A fiduciary financial advisor has a legal or professional obligation, depending on the relationship and applicable standard, to act in the client’s best interests.
However, consumers should not assume that every person using the term “advisor” is automatically subject to the same fiduciary obligation in every interaction.
CFP Board states that CFP® professionals commit to act as fiduciaries when providing financial advice to clients.
Ask for the obligation in writing.
Also ask:
- When does the fiduciary obligation apply?
- To which services?
- How is the professional compensated?
- What conflicts exist?
- What products or investments can they recommend?
These questions can reveal much more than a job title.
Financial Advisor vs Investment Advisor: Which Services Do You Need?
Consider three hypothetical situations.
Situation 1: “I Just Need Investment Help”
You have accumulated $300,000 and want assistance building a diversified portfolio.
Your primary need may be investment advice and portfolio management.
You may not need comprehensive planning if your other financial affairs are already organized.
Situation 2: “I’m 10 Years From Retirement”
You have investments, but you need to know:
- How much you can spend
- When to claim Social Security
- How taxes will affect withdrawals
- Whether your investments are appropriately positioned
This requires broader retirement planning and financial planning.
Situation 3: “My Business and Personal Wealth Are Connected”
You own a company, have significant investments and need to coordinate:
- Business value
- Personal investments
- Taxes
- Retirement
- Estate considerations
This may call for a broader wealth management relationship.
The key is matching the scope of professional help to the complexity of your financial situation.
Questions to Ask Before Hiring Any Financial Professional
Before signing an agreement, ask these questions.
1. What exactly do you provide?
Do you provide investment management, financial planning, tax planning, retirement planning, or some combination?
2. How are you paid?
Ask for a clear explanation of every fee and potential compensation source.
3. What credentials do you have?
Ask about licenses, certifications and professional designations.
4. Are you a registered investment adviser?
If applicable, ask about the firm’s registration and review its regulatory disclosures.
5. Are you acting as a fiduciary?
Do not assume. Ask.
6. What conflicts of interest exist?
Ask whether compensation could influence recommendations.
7. Who actually makes investment decisions?
Understand whether you make every decision, the advisor recommends investments, or the advisor has discretionary authority.
8. What happens if my financial situation changes?
Good planning should be able to evolve with your life.
How to Research a Financial Professional
Don’t stop at a website biography.
For U.S. investment professionals, regulatory information can provide important context.
The SEC explains that Form ADV contains information about registered investment advisers, including business practices, fees, other activities and disciplinary history.
FINRA also points consumers toward Form CRS, which can help compare brokerage and advisory relationships, including services, costs, conflicts and standards of conduct.
Research should therefore be part of your hiring process.
How Synergistic Financial Advisors Fits Into the Bigger Picture
Synergistic Financial Advisors approaches financial services from a broader perspective rather than treating every client question as simply an investment-selection problem.
Its approach can connect financial planning, investment management, portfolio management, retirement planning, wealth management and tax planning around a client’s broader objectives.
For individuals searching for financial advisors near me, the goal should be to find a professional relationship that matches the complexity of their needs.
Someone searching for a financial planner near me may need comprehensive planning.
Someone searching for an investment advisor may primarily need investment management.
Someone searching for a financial consultant near me may need targeted analysis or strategic guidance.
And someone looking for an independent financial advisor may want to understand the firm’s ownership, product availability and potential conflicts before establishing a relationship.
Synergistic Financial Advisors can help clients evaluate financial decisions through a combination of advisory, planning, investment and analytical perspectives.
Explore Synergistic Financial Advisors
For clients seeking broader strategic support, the important question is not which title sounds most impressive.
It is whether the professional’s capabilities match the financial decisions you actually need to make.
Explore SFA Financial Advisory Services
The Three-Question Test
If you are still confused, use this simple test.
Do you primarily need investments managed?
Look for investment advisory and investment management capabilities.
Do you need a complete roadmap for your finances?
Look for comprehensive financial planning and a qualified financial planner.
Do you need both?
Look for a firm capable of integrating planning with investment management and broader financial services.
That third category is increasingly relevant for families whose finances span investments, retirement, taxes, businesses and estate considerations.
The Bottom Line
Financial advisor, investment advisor and financial planner are not interchangeable labels in every regulatory or business context — but their services can overlap significantly.
The SEC itself emphasizes that consumers should look beyond titles and understand the actual services, fees and relationship involved.
The most useful comparison is therefore:
Title → Credentials → Services → Fees → Conflicts → Legal standard → Actual fit
A certified financial planner may be particularly relevant when you want comprehensive planning and value the CFP® certification framework.
An investment adviser may be relevant when your primary need is securities advice and ongoing investment management.
A broader financial advisor relationship may encompass some or all of these services, depending on the firm.
There is no universal title that solves every financial problem.
Your financial situation should determine the type and scope of professional help you seek.
And before you hire anyone, ask the questions that matter:
What do you do? How are you paid? What credentials do you hold? What conflicts exist? What standard applies to our relationship?
Those answers are far more important than the title printed on a business card.