Building significant wealth creates opportunities.
It also creates complexity.
Once your financial life includes substantial investment portfolios, business interests, real estate, multiple account types, concentrated stock positions, estate considerations, charitable goals, and potentially assets across different jurisdictions, simply choosing good investments is no longer enough.
This is where wealth management for high-net-worth individuals becomes fundamentally different from basic investment management.
The central question changes from:
“Where should I invest my money?”
to:
“How should my entire financial life work together?”
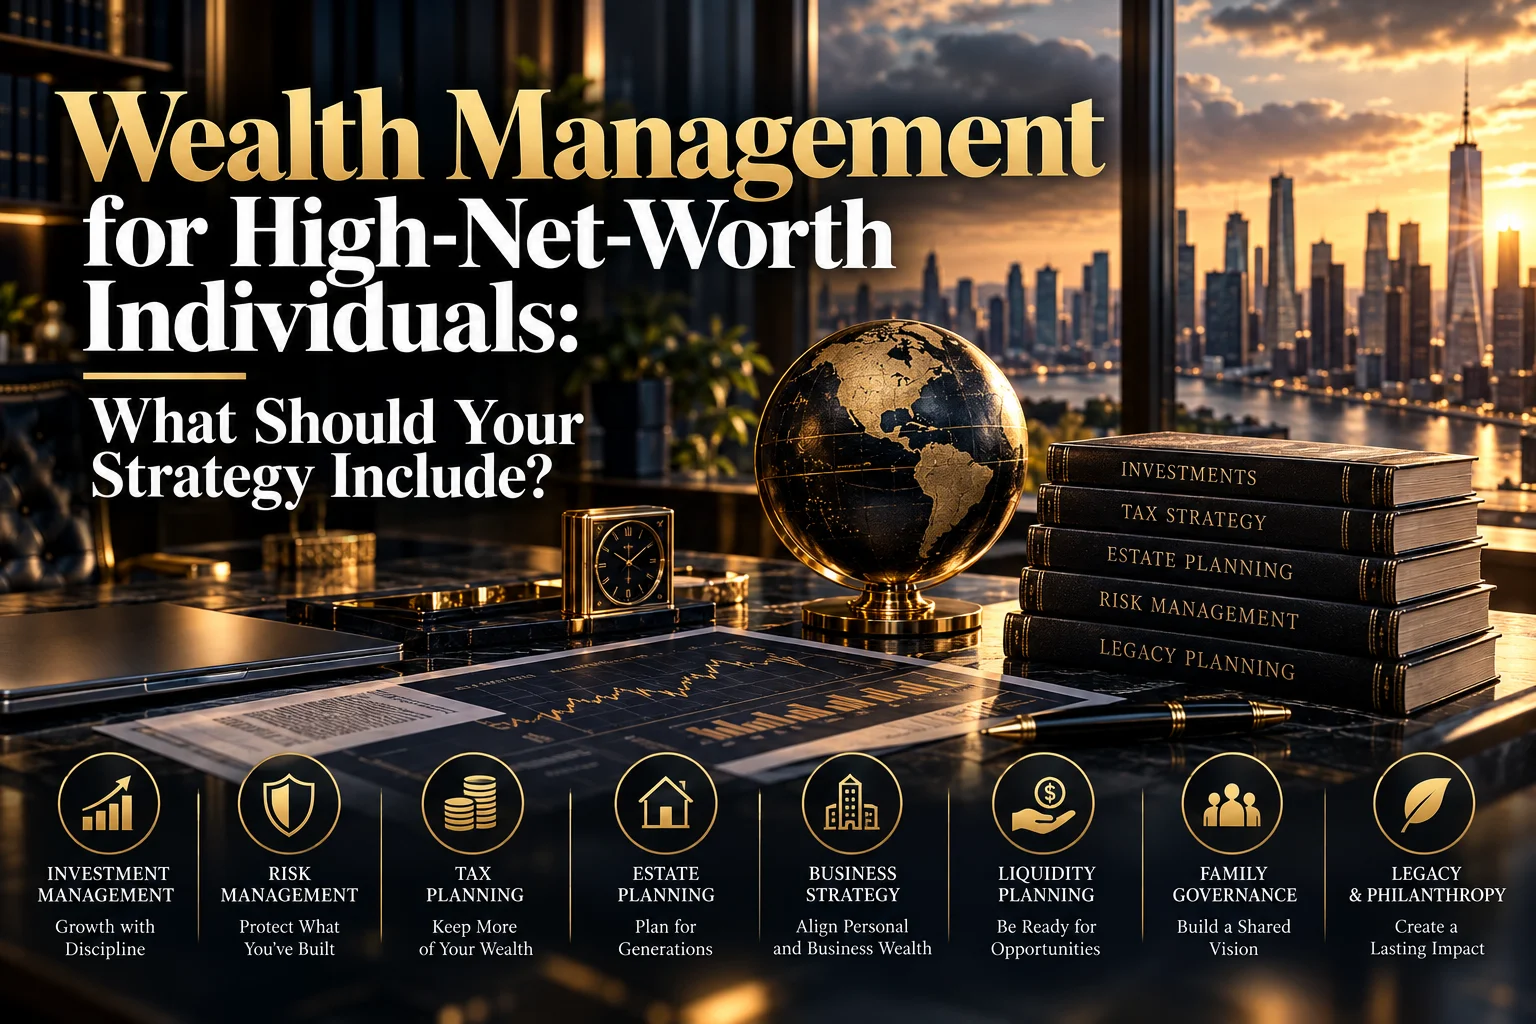
For high-net-worth individuals and families, a strong wealth strategy should coordinate investment decisions with taxes, liquidity, estate planning, risk management, retirement, business interests, family goals, and ultimately the transfer or use of wealth.
In other words:
A large portfolio is not automatically a wealth strategy.
Here are the major components a comprehensive high-net-worth wealth management plan should consider.
1. Start With the Purpose of the Wealth
Before deciding how assets should be invested, it helps to determine what the wealth is supposed to accomplish.
That may sound obvious, but high-net-worth families often have several competing objectives.
You may want to:
- Maintain your current lifestyle
- Fund retirement
- Preserve capital across generations
- Grow wealth aggressively
- Sell or expand a business
- Purchase additional real estate
- Fund children’s or grandchildren’s education
- Support charitable causes
- Create financial independence for family members
- Leave a legacy
- Generate dependable portfolio income
Those objectives do not necessarily require the same investment strategy.
Someone who intends to spend a substantial portion of their assets during retirement has different liquidity requirements from a business owner who hopes to transfer most of a family enterprise to the next generation.
Effective financial planning therefore begins with goals before products.
2. Build an Investment Strategy Around Total Wealth
For many investors, portfolio management means managing a brokerage account.
For a high-net-worth household, that view can be too narrow.
Total wealth may include:
- Public stocks
- Bonds
- Cash
- Retirement accounts
- Employer equity
- Restricted stock
- Private businesses
- Commercial or residential real estate
- Private investments
- Trust assets
- International investments
- Insurance-related assets
These holdings should not always be analyzed independently.
Imagine an executive whose investment account appears diversified but whose company stock represents 40% of total family wealth.
Or a business owner who owns several investment funds while 70% of net worth remains tied to one private company.
The brokerage account might look diversified.
The family’s balance sheet may not be.
FINRA specifically warns that concentration risk can arise from a single investment, sector, correlated assets, employer stock, or illiquid holdings. It recommends examining diversification both across and within asset classes.
A sophisticated portfolio management process should therefore begin with a household-level balance sheet rather than looking at each account in isolation.
3. Manage Concentration Risk Without Ignoring Taxes
Concentrated wealth is common among successful investors.
Founders may own large positions in their companies.
Executives may accumulate employer shares through compensation plans.
Families may have substantial exposure to a particular industry.
Real estate investors may have most of their wealth tied to property.
The challenge is that selling concentrated positions can potentially create significant tax liabilities.
But refusing to diversify solely because of taxes can leave the investor exposed to large losses.
This creates one of the most important trade-offs in high-net-worth investment management:
How much investment risk should you accept to avoid triggering taxes?
Possible planning approaches may involve gradually reducing concentration, coordinating gains with realized losses, gifting appreciated assets where appropriate, adjusting other areas of the portfolio, or building diversification over time.
There is rarely a universal answer.
The investment, tax, liquidity, estate, and personal consequences need to be considered together.
4. Make Tax Planning Part of Investment Management
For high-net-worth investors, gross investment returns tell only part of the story.
What ultimately matters is how much wealth remains available after taxes, costs, inflation, and spending.
That makes tax planning an important component of long-term wealth management.
A tax-aware strategy can consider issues such as:
Asset Location
Different investments can have different tax characteristics.
Depending on an individual’s circumstances, certain assets may be better suited to taxable accounts while others may be better located in tax-advantaged accounts.
The objective is not simply to select investments.
It is to determine where they should be held.
Capital Gains Management
Portfolio changes can create taxable gains.
A coordinated approach may consider:
- Holding periods
- Realized gains and losses
- Portfolio rebalancing
- Tax-loss harvesting opportunities
- Charitable contributions
- Expected future income
- Major liquidity events
Tax-Loss Harvesting
Realized investment losses can potentially offset realized capital gains.
The IRS also permits qualifying net capital losses exceeding capital gains to offset up to $3,000 of other income annually, with eligible unused losses generally carried forward. Investors must also account for wash-sale rules when purchasing substantially identical securities around a loss-generating sale.
Tax considerations should influence investment implementation.
They should not completely replace investment logic.
5. Treat Estate Planning as a Wealth Strategy—Not Just a Legal Document
Estate planning becomes increasingly important as family wealth grows.
It is not merely about preparing a will.
A comprehensive estate strategy may address:
- Who receives assets
- When beneficiaries receive them
- How assets are controlled
- Potential estate and gift taxes
- Trust structures
- Business succession
- Charitable intentions
- Family governance
- Incapacity planning
- Beneficiary designations
- Life insurance
- Intergenerational wealth transfer
This is especially relevant in 2026.
For U.S. federal estate and gift tax purposes, the basic exclusion amount is $15 million per individual in 2026, up from $13.99 million for 2025. The IRS also lists the 2026 annual gift-tax exclusion at $19,000 per recipient.
Those figures should not be interpreted as a reason to delay planning until a family reaches a particular level of wealth.
Estate planning can still matter well below the federal estate-tax threshold because it also determines control, succession, protection, administration, and family outcomes.
High-net-worth families should generally coordinate estate strategies with qualified estate attorneys and tax professionals rather than treating investment planning and estate planning as separate projects.
6. Develop a Liquidity Strategy
An individual can be wealthy on paper and still face liquidity problems.
Consider someone whose wealth includes:
- A private company
- Several investment properties
- Private equity holdings
- Long-term investments
- Restricted shares
The balance sheet may be substantial, but relatively little may be immediately available for spending, taxes, opportunities, or unexpected obligations.
FINRA notes that liquidity risk matters because some investments—including certain private placements and non-traded investments—may be difficult or costly to sell quickly.
A high-net-worth liquidity plan may therefore separate capital into different purposes:
Immediate liquidity: cash available for expected spending and emergencies.
Strategic reserves: money available for taxes, real estate purchases, business needs, or investment opportunities.
Long-term capital: assets intended primarily for growth or intergenerational wealth.
This structure can reduce the likelihood that long-term investments must be sold at an inconvenient time.
7. Evaluate Alternative Investments Carefully
High-net-worth investors frequently have access to investments that may not be available to all retail investors.
These can include:
- Private equity
- Private credit
- Venture capital
- Hedge-fund strategies
- Private real estate
- Structured products
- Other private investments
Alternatives may potentially expand the opportunity set or provide different return drivers.
But “exclusive” does not mean “better.”
Alternative investments may introduce:
- Illiquidity
- Higher fees
- Complex structures
- Leverage
- Valuation uncertainty
- Limited disclosure
- Long lock-up periods
- Concentration risk
FINRA cautions that alternative and emerging investment products can have materially different liquidity, strategy, performance, concentration, disclosure, and fee risks.
The right question is therefore not:
“Can I access alternative investments?”
It is:
“What specific role does this investment play in my overall portfolio?”
If that question cannot be answered clearly, complexity alone should not be mistaken for sophistication.
8. Coordinate Business Wealth With Personal Wealth
For entrepreneurs, the business may be both the source of wealth and the largest financial risk.
This creates a unique planning challenge.
A successful company may represent:
- Current income
- Future retirement funding
- Family legacy
- The majority of net worth
- A potential future liquidity event
That means personal wealth management cannot be separated from business strategy.
Important issues can include:
- Business valuation
- Succession
- Exit planning
- M&A opportunities
- Capital needs
- Personal diversification
- Liquidity after a sale
- Tax implications
- Estate planning
- Investment of sale proceeds
One of the most important questions a business owner can ask is:
If my company represents most of my wealth, how financially independent am I from the company?
SFA’s corporate finance, valuation, M&A advisory, and portfolio capabilities can be particularly relevant where business and personal wealth intersect.
9. Protect Wealth Against Risks That Investments Cannot Solve
Not every financial risk belongs inside an investment portfolio.
High-net-worth planning may also require evaluating:
- Property and casualty coverage
- Liability exposure
- Umbrella coverage
- Life insurance
- Disability or income protection
- Business insurance
- Estate liquidity needs
- Cybersecurity and fraud exposure
Insurance should not automatically be viewed as an investment.
Its primary role may instead be risk transfer.
For substantial estates or business owners, the appropriate insurance structure can be part of broader financial and estate planning.
10. Create a Charitable Giving Strategy
Philanthropy can become an important component of wealth planning.
Rather than treating charitable donations as isolated year-end transactions, high-net-worth individuals may benefit from integrating giving with investment, estate, and tax planning.
Depending on circumstances and professional advice, strategies may involve:
- Direct charitable contributions
- Gifts of appreciated securities
- Donor-advised funds
- Charitable trusts
- Private foundations
- Legacy giving
The appropriate approach depends on the donor’s goals, assets, desired level of control, timeframe, tax situation, and administrative preferences.
The starting point should always be the philanthropic objective.
The tax benefit should support the strategy—not define its purpose.
11. Plan for Wealth Transfer Before It Becomes Urgent
The financial side of inheritance is only part of successful wealth transfer.
Families should also consider whether the next generation is prepared to manage the wealth.
Questions may include:
- What values should the wealth support?
- How much financial information should children receive?
- At what age should beneficiaries gain control?
- Should assets be transferred outright or through trusts?
- Who will manage family businesses?
- Who should make financial decisions if the current wealth creator cannot?
- How can conflict between family members be reduced?
These are not primarily investment questions.
They are governance questions.
And for substantial family wealth, governance can be just as important as portfolio performance.
12. Build One Coordinated Team
High-net-worth individuals may work with several professionals:
- Financial advisor
- Investment advisor
- CPA or tax professional
- Estate attorney
- Insurance professional
- Business advisor
- Corporate finance specialist
- Trustee
The problem arises when each professional sees only one piece of the financial picture.
The tax advisor may recommend one strategy.
The investment manager may implement another.
The estate attorney may create documents that no longer reflect the actual assets.
A strong wealth-management structure connects these areas.
Think of it as a financial architecture rather than a collection of individual products.
The High-Net-Worth Wealth Management Checklist
A useful annual review should consider:
| Area | Key Question |
|---|---|
| Financial goals | What is the wealth ultimately supposed to accomplish? |
| Asset allocation | Does the portfolio match objectives and risk capacity? |
| Concentration | Is too much wealth dependent on one company, sector, property, or business? |
| Diversification | Are risks diversified across and within asset classes? |
| Taxes | Are investment decisions being evaluated on an after-tax basis? |
| Liquidity | Is enough capital readily available for expected obligations and opportunities? |
| Estate planning | Do current documents and structures reflect today’s family and assets? |
| Wealth transfer | Is there a strategy for transferring assets and responsibility? |
| Business interests | Are personal and business finances coordinated? |
| Alternatives | Does each complex investment serve a specific portfolio purpose? |
| Insurance | Are major risks appropriately transferred or retained? |
| Philanthropy | Is charitable giving coordinated with the broader financial plan? |
| Professional team | Are advisors working toward the same objectives? |
What Should High-Net-Worth Wealth Management Actually Deliver?
The objective should not simply be outperforming an index every year.
A comprehensive strategy should help answer bigger questions:
Do I have enough liquidity?
Am I taking risks I do not need to take?
Is too much of my wealth concentrated in one area?
Are investment decisions being made tax-efficiently?
What happens to my assets if something happens to me?
How should my business and personal wealth work together?
How much should eventually pass to family or charity?
Can my wealth support my lifestyle without undermining long-term goals?
That is the difference between managing investments and managing wealth.
How SFA Can Support a High-Net-Worth Strategy
Synergistic Financial Advisors approaches financial decision-making across multiple areas including portfolio management, financial advisory, corporate finance, valuation, investment research, and strategic analysis.
For high-net-worth investors and business owners, that broader perspective can be especially valuable because the investment portfolio often represents only one component of total wealth.
A coordinated strategy can help connect:
Investment Management → Tax Awareness → Business Wealth → Liquidity → Estate Objectives → Long-Term Legacy