A profitable business can create income.
A valuable business can create net worth.
But neither automatically creates personal financial security.
That distinction matters because many entrepreneurs spend years building revenue, hiring employees, reinvesting profits, and growing the value of their companies while comparatively little attention is given to the owner’s personal balance sheet.
The result can be surprising:
A business owner may appear wealthy while having most of that wealth trapped inside one company.
This is why effective financial planning for business owners needs to go beyond budgeting, bookkeeping, or finding the next growth opportunity.
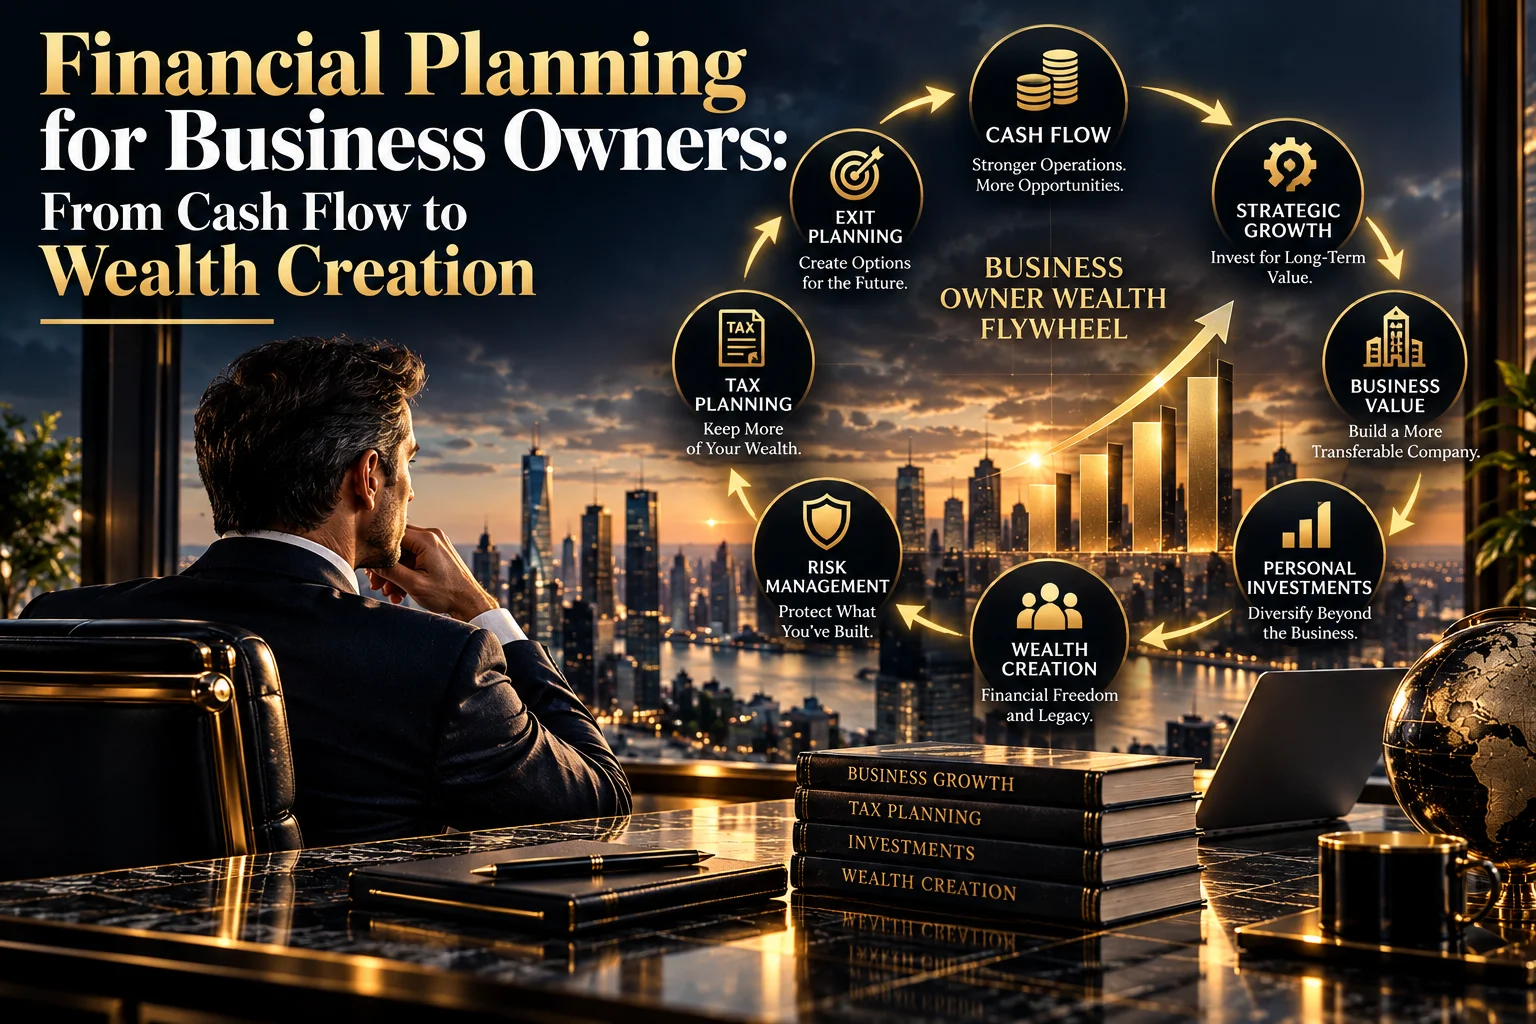
The real objective is to create a financial system that connects:
Cash Flow → Reserves → Tax Strategy → Business Growth → Personal Investments → Business Value → Exit Planning → Long-Term Wealth
We call this the Business Owner Wealth Flywheel.
Each stage supports the next.
And if one part is weak, the owner’s overall financial position can remain vulnerable—even when the business itself is successful.
1. Start With Cash Flow, Not Revenue
Revenue attracts attention.
Cash keeps a business alive.
A company can report strong sales and even accounting profits while still struggling to meet payroll, debt payments, taxes, supplier obligations, or expansion costs.
SBA-supported small-business financial education emphasizes the distinction between profit and available cash and recommends using cash-flow projections, accounts-receivable management, accounts-payable management, and financial statements to identify shortages before they become serious problems.
For a business owner, that means financial planning should begin with a clear understanding of:
- Cash entering the business
- Fixed operating expenses
- Variable costs
- Accounts receivable
- Accounts payable
- Debt payments
- Payroll
- Tax obligations
- Capital expenditures
- Owner distributions
- Seasonal fluctuations
Ask a Better Question
Instead of asking:
“Did the company make money this month?”
ask:
“How much cash did the company generate after meeting its obligations, and what should happen to that cash next?”
That second question is where wealth creation begins.
2. Build a Business Liquidity System
Growing businesses require capital.
But keeping every available dollar inside the company can expose the owner to unnecessary financial risk.
A business-owner liquidity strategy can divide available capital into several buckets.
Operating Capital
Money needed to fund normal business operations.
Emergency Liquidity
Funds available for unexpected disruptions, customer delays, equipment problems, or temporary revenue weakness.
Tax Reserves
Money specifically reserved for upcoming tax obligations.
Growth Capital
Funds earmarked for hiring, expansion, inventory, technology, acquisitions, or other investments expected to improve the business.
Owner Wealth Capital
Cash that can be intentionally moved from the business into the owner’s personal financial plan.
That final category is often overlooked.
If every dollar of excess cash is continually reinvested into the company, the owner’s personal wealth may remain dangerously dependent on one asset: the business.
3. Separate Business Success From Personal Wealth
Consider two business owners.
Both own companies worth $5 million.
Owner A
- $4.7 million of net worth is tied to the business.
- $200,000 is held in cash.
- $100,000 is invested outside the company.
Owner B
- Owns the same $5 million business.
- Has also built a diversified investment portfolio.
- Maintains personal liquidity.
- Contributes consistently toward retirement.
- Owns assets that do not depend on the company’s performance.
Both may have similar business valuations.
Their personal financial risk is very different.
FINRA describes concentration risk as the possibility of amplified losses when a large portion of wealth is tied to a single investment, asset class, or market segment. Diversification across and within asset classes can help manage that risk.
For entrepreneurs, the company itself may represent the largest concentration of all.
A central objective of wealth management for a business owner should therefore be:
Gradually create wealth that exists independently from the company.
4. Create an Intentional Owner-Pay Strategy
Business owners frequently move money between personal and business accounts based on immediate needs.
That can make it difficult to understand:
- The company’s real operating performance
- The owner’s personal spending requirements
- How much capital is actually available for growth
- How much can be invested
- Whether lifestyle spending is rising with business revenue
A better approach is to establish a deliberate compensation and distribution framework appropriate to the business structure.
The specifics depend on whether the company operates as a sole proprietorship, partnership, S corporation, C corporation, LLC, or another structure.
That makes coordination with an accountant or tax professional important.
But from a financial planning perspective, the objective is straightforward:
The owner’s personal financial life should not depend on unpredictable withdrawals from the company.
5. Turn Tax Planning Into a Year-Round Process
For many entrepreneurs, taxes are one of the largest recurring cash outflows.
Yet tax planning is often treated as a once-a-year exercise.
That can create unnecessary pressure.
The IRS describes the U.S. federal income-tax system as pay-as-you-go. Sole proprietors, partners, and S corporation shareholders who expect to owe sufficient tax may need to make estimated payments during the year, and underpayment can result in penalties.
Business-owner tax planning can involve coordination around:
- Estimated tax payments
- Business structure
- Compensation
- Retirement-plan contributions
- Capital expenditures
- Investment gains and losses
- Charitable giving
- Business-sale timing
- Estate planning
The objective is not simply to minimize this year’s tax bill.
It is to make tax decisions in the context of long-term wealth.
A strategy that saves taxes today but traps more capital inside an already concentrated business may not always improve the owner’s overall financial position.
6. Use Retirement Plans as a Wealth-Building Tool
Business owners often have more retirement-plan choices than they realize.
Depending on the company, workforce, income, and plan design, possibilities can include:
- SEP IRA
- SIMPLE IRA
- Solo or one-participant 401(k)
- Traditional 401(k)
- Profit-sharing arrangements
- Defined benefit plans
For 2026, the IRS increased the basic employee elective-deferral limit for 401(k) plans to $24,500.
The standard age-50-and-over catch-up contribution is $8,000, while eligible participants ages 60 through 63 can have a higher catch-up limit of $11,250 in 2026.
The overall defined-contribution-plan limit is $72,000, excluding applicable catch-up contributions.
For SEP plans, employer contributions generally cannot exceed the lesser of 25% of qualifying compensation or $72,000 for 2026, subject to the specific rules for employees and self-employed individuals.
These plans can serve two purposes simultaneously:
Build wealth outside the business and support tax-efficient long-term saving.
The appropriate plan depends heavily on employee structure and tax circumstances, so plan design should be reviewed with qualified retirement and tax professionals.
7. Decide How Much to Reinvest in the Business
Reinvestment can be one of the best uses of capital.
But not every reinvestment creates value.
Before putting another $100,000 into the company, consider:
What return should this capital realistically produce?
Potential investments might include:
- New employees
- Equipment
- Software
- Marketing
- Inventory
- Geographic expansion
- Product development
- Acquisitions
A business owner should compare those opportunities with alternative uses of capital.
For example:
Option A: Invest another $200,000 into the business.
Option B: Pay down expensive debt.
Option C: Add the money to personal investments.
Option D: Maintain additional liquidity.
Option E: Use capital for an acquisition.
The best decision depends on expected return, risk, liquidity, business concentration, and the owner’s wider goals.
This is where corporate finance and personal investment management begin to overlap.
8. Know What Your Business Is Actually Worth
Many owners mentally assign a value to their businesses based on revenue, years of work, competitor transactions, or what they need the business to be worth for retirement.
Buyers do not necessarily value businesses that way.
The SBA identifies several common valuation approaches, including:
- Income approach: based on projected earnings and risk
- Market approach: compares the company with similar businesses or transactions
- Asset approach: considers business assets minus liabilities
It also notes that intangible assets—including brand value, intellectual property, customer information, and expected future revenue—can contribute to valuation.
A formal business valuation can help an owner answer several important questions:
- Is my company worth enough to fund my intended retirement?
- What factors are increasing or reducing its value?
- Is the company overly dependent on me?
- Is customer concentration creating risk?
- Are margins attractive to potential buyers?
- What could make the business more valuable over the next five years?
Knowing today’s value provides a starting point for building tomorrow’s value.
9. Build a Business That Can Operate Without You
One of the biggest differences between owning a job and owning a valuable enterprise is dependency.
If customers, employees, suppliers, and major decisions all depend on the founder, a potential buyer may see risk.
A more transferable company typically benefits from:
- Strong management
- Documented processes
- Reliable financial reporting
- Diverse customers
- Recurring or predictable revenue where applicable
- Employee retention
- Clear contracts
- Operational systems
- Reduced founder dependency
Improving these areas can potentially benefit both day-to-day operations and eventual exit value.
That is why exit planning should begin years before a sale, not when an owner suddenly decides to retire.
10. Create Personal Investments Outside the Business
Once adequate operating capital and reserves exist, business owners can establish a systematic strategy for moving a portion of wealth outside the company.
Depending on objectives and risk tolerance, a personal portfolio may include:
- Public equities
- High-quality fixed income
- Cash and short-term reserves
- Real estate
- Retirement accounts
- Other diversified investments
The objective is not to stop believing in the company.
It is to avoid making the owner’s retirement, family security, future lifestyle, and investment portfolio all dependent on the same economic asset.
For many entrepreneurs, portfolio management should therefore be considered alongside business growth—not after the business is sold.
11. Protect the Business and the Owner
Entrepreneurs should also consider what happens if the financial plan is interrupted.
Potential risks include:
- Disability
- Death of an owner
- Loss of a key employee
- Lawsuits
- Property damage
- Cyber events
- Business interruption
- Partnership disputes
Depending on the circumstances, planning may involve insurance, buy-sell agreements, succession arrangements, emergency liquidity, and legal structures.
The objective is to protect both sides of the balance sheet:
the company creating the wealth and the family depending on it.
12. Build an Exit Strategy Before You Need One
Every business owner eventually exits.
The only uncertainty is how.
Possible outcomes include:
- Sale to an outside buyer
- Sale to management
- Transfer to family
- Merger
- Private-equity transaction
- Gradual ownership transition
- Liquidation
A thoughtful exit plan should consider:
Business value
Timing
Tax implications
Personal liquidity
Post-sale investment strategy
Retirement income
Family and estate goals
What the owner wants life to look like after the transaction
Selling a company can convert an entrepreneur’s largest illiquid asset into a significant pool of investable capital.
That requires a completely different financial strategy.
Planning for the money after the sale can therefore be just as important as negotiating the sale itself.
The Business Owner Wealth Flywheel
A useful way to view the entire strategy is:
1. Generate Healthy Cash Flow
Build profitable, sustainable operations.
↓
2. Maintain Appropriate Liquidity
Protect the company from short-term shocks.
↓
3. Allocate Capital Intentionally
Choose between reinvestment, debt reduction, reserves, and owner distributions.
↓
4. Manage Taxes and Retirement
Use available planning structures intelligently.
↓
5. Build Wealth Outside the Business
Reduce dependence on one company.
↓
6. Increase Business Value
Improve profitability, systems, management, and transferability.
↓
7. Prepare for Exit or Succession
Create options rather than being forced into a transaction.
↓
8. Convert Business Success Into Lasting Wealth
Coordinate investment, retirement, estate, and legacy goals.
Then repeat the process as the company and owner’s financial position evolve.
Financial Planning Checklist for Business Owners
| Area | Question to Ask |
|---|---|
| Cash Flow | Do I know where business cash is going each month? |
| Liquidity | Could the company handle an unexpected disruption? |
| Tax Planning | Are tax obligations being planned throughout the year? |
| Owner Pay | Is my compensation/distribution strategy intentional? |
| Retirement | Am I using an appropriate business retirement plan? |
| Reinvestment | Are new business investments earning an acceptable return? |
| Personal Wealth | Am I building assets outside my company? |
| Concentration Risk | What percentage of my net worth depends on the business? |
| Business Valuation | Do I know what the company is realistically worth? |
| Risk Management | What happens if I cannot work or a key person leaves? |
| Succession | Who could operate or own the business without me? |
| Exit Planning | How and when would I ideally leave the business? |
| Post-Exit Wealth | What happens financially after a sale? |
How SFA Can Help Business Owners Connect the Pieces
Business owners often work with an accountant for taxes, an attorney for legal matters, a banker for financing, and an investment professional for personal assets.
The challenge is making those decisions work together.
Synergistic Financial Advisors’ broader capabilities—including corporate finance, business valuation, M&A advisory, capital sourcing, financial advisory, research, and portfolio management—can help connect the corporate and personal sides of financial decision-making.
That matters because an entrepreneur’s financial life cannot always be separated neatly into “business money” and “personal money.”
The same company may represent:
Income + Net Worth + Retirement + Legacy + Investment Risk
A coordinated strategy can help turn that concentration into long-term financial flexibility.
Frequently Asked Questions
What is the most important financial planning priority for a business owner?
Healthy cash flow and liquidity generally come first because the company needs sufficient resources to operate. From there, owners can build tax, retirement, investment, risk-management, and exit strategies.
Should business owners invest outside their companies?
For many owners, diversification outside the business can help reduce concentration risk. The appropriate amount depends on business needs, personal goals, liquidity, risk tolerance, and tax considerations.
When should a business owner start exit planning?
Ideally, well before an intended sale or transition. Improving financial reporting, management systems, margins, customer diversification, and owner independence can take years and may influence business value.
Is a business valuation only necessary before selling?
No. Periodic valuation can help with financial planning, succession, ownership transitions, insurance decisions, strategic planning, and measuring whether business value is growing toward the owner’s long-term target.
Can retirement planning and business planning be combined?
Yes. For many owners, retirement accounts, business value, eventual sale proceeds, personal investments, and Social Security can all contribute to future retirement resources. They should be evaluated as parts of one financial plan.
Final Thoughts
For a business owner, wealth creation should not be measured only by revenue.
It should not even be measured only by company valuation.
The stronger measure is whether the success of the business is gradually creating a more resilient personal financial position.
That means managing cash carefully.
Allocating capital intentionally.
Planning for taxes.
Building retirement assets.
Diversifying outside the company.
Increasing transferable business value.
And preparing for an eventual exit long before it becomes necessary.
The ultimate goal is simple:
Your business should create wealth—not become the only place your wealth exists.
With coordinated financial planning, corporate finance, investment management, and long-term strategy, business owners can move from simply operating a successful company to building durable wealth that can support their family, retirement, future opportunities, and legacy.